- Home
-
Private banking
- Market view
- Insights

Succession rarely fails on the day control changes hands. The most damaging mistakes tend to come earlier - often in the form of assumptions that can prevent families from making difficult but necessary decisions. Here are four of the most common.
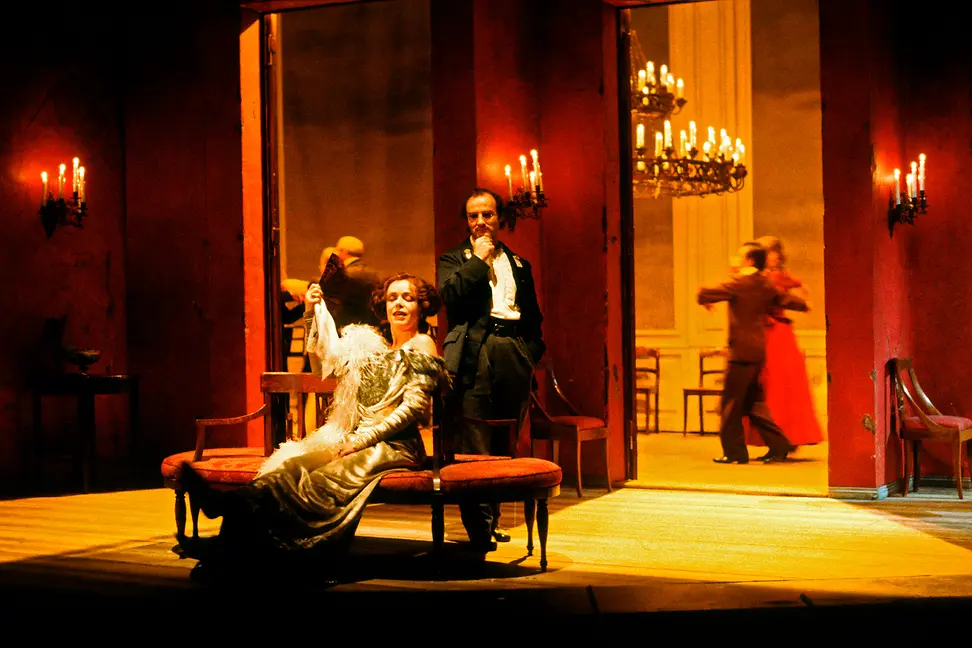
In his play "The Cherry Orchard", Anton Chekhov explores what happens when succession is left too late. In one scene, a ball is in full swing at a Russian country estate. A band is playing and couples are dancing. The estate, which is famous for its cherry orchard, is heavily in debt and had gone to auction earlier that day.
Lopakhin, a merchant whose father and grandfather had been serfs on the estate, had suggested that the owners cut down the cherry trees, divide the land into plots, build dachas on them and rent them out. The income could have saved the estate.
But the family had found the idea beneath them. Becoming landlords did not fit with their sense of who they were. And so they postponed the decision until it was taken out of their hands. In the end, Lopakhin bought the estate himself. As the curtain falls, the audience hears the sound of trees being cut down.
The Cherry Orchard" is a story about the decline of Russia's landed gentry and the rise of the new merchant class. But it is also a warning about the danger of holding on for too long. The family is so attached to the estate that it ultimately loses it. It isn't a war or a crop failure that seals its fate. Hesitation does. Chekhov called the play a comedy.
Elke Willi, Head of Wealth Planning at LGT in Austria, advises entrepreneurial families on wealth and succession. In her work, she sees four assumptions in particular that can prevent families from making the decisions required for a successful handover.
This is the first of three articles in our "Ready for succession" series tracing the path from holding on to letting go. Part one explores three questions that families should answer before a handover. Part two examines four common mistakes. Part three sets out ten steps that successors and outgoing leaders can take to prepare for the transition.
In 2007, Luis R. Gómez-Mejía and his colleagues published a study involving family-owned olive oil mills in southern Spain. Their data covered 1237 businesses over a period of 54 years.
The businesses faced a choice. They could join a co-operative and reduce their financial risk but give up some control. Or they could remain independent, retain control and accept greater risk. They tended to choose the latter.
In other words, they chose greater financial risk rather than surrender control. As the researchers put it, family businesses can be "risk willing and averse at the same time". Why? Because money wasn't the only thing at stake. The families were also protecting control, identity, influence and the possibility of passing the business on. Researchers call this non-financial value "socioemotional wealth".
That same fear of losing control can also make succession difficult. If control has become part of someone's identity, giving it up is hard, and an "I'll sort that out later" attitude can follow. Putting a date on a handover makes that loss real.
But the next generation needs clarity. "I call it a handover governance roadmap," says Willi. The family needs a binding plan. What role should the successor take on? Which responsibilities should they assume and when? The plans should also set out when the current head of the company will step back from running the day-to-day business.
Only then can the next generation decide whether they even want that responsibility. "If someone's still in the office every day at 85 and calling the shots, it won't end well."
Without a plan, successors can get stuck in limbo. They may work for the business, but never quite get to lead it. Some eventually give up and walk away.
A better approach is to transfer responsibility gradually. Start with a project, for example. Then give the successor responsibility for a department, and eventually, the business. This gives them the chance to grow into the role instead of spending years waiting for it.
Leaving a succession to children often means passing on more than just ownership. They may also inherit unresolved questions about roles, power and long-standing family conflicts.
By the time the children have to make those decisions, the founder who once had the final say - or could settle disputes - may no longer be there to do so.
In 1988, organisational psychologist Ivan Lansberg gave this pattern a name: "the succession conspiracy". It works like this:
Their motives differ, but the result is a collective silence around succession.
In one of Lansberg's case studies, a founder appointed his eldest daughter as his successor but did not give her the guidance or training she needed for the role. By appointing her, he was able to tell himself he had dealt with the issue of succession. But by holding her back, he retained control. On paper, a successor was in place. In practice, she was never given the opportunity to grow into the role. The case study illustrates how intentions and behaviour can diverge.
Tax advisors can explain tax implications. Lawyers can turn decisions into contracts. A bank can advise on how to structure assets. All three have an important role to play. But none of them can decide for the family who will lead the business in future, who will own what or how family members should work together once control passes on to the next generation.
"Ideally, a neutral facilitator should support the family when it draws up a family constitution," says Willi. A facilitator can bring different interests into the conversation. They can also make sure that less vocal family members are heard.
Once the family has agreed on its roles, objectives and rules, those decisions can be implemented. The specialists can play their part: the tax advisor addresses the tax implications, the lawyer draws up the contracts and the bank advises on how the assets should be structured.
Willi gives an example of an entrepreneur with three well-educated children. Her daughter chose a career outside of the family business; her two sons were already working in it.
The entrepreneur brought in an expert from the US to help the family draft a family constitution. They started with some fundamental questions: What did the family stand for? Who wanted to work in the business? How did they want to work together in the future?
Only then were the contracts drawn up, formalising what the family had decided.
Dividing things up equally may seem fair. But when it comes to succession, it may be anything but.
In a 1990 experiment at Cornell University, half of the participants were given a coffee mug. The other half were asked how much they would pay for one.
The difference was striking. Mug owners wanted a median of USD 5.25 to part with their mugs. Buyers were willing to pay only USD 2.25 to USD 2.75. Very few mugs changed hands.
The experiment became a classic example of the "endowment effect": once something belongs to us, we tend to value it more highly.
Just a few minutes of ownership were enough to produce the effect. The attachment to a business built over a lifetime is far stronger.
The older generation sees decades of work, risk and family history. An heir or buyer sees a company that must be valued and kept going. This has little to do with greed and a great deal to do with attachment. And that attachment can shape perceptions of what constitutes a fair division.
Succession brings another complication. One owner in one generation may be replaced by several siblings in the next. A generation later, ownership may spread to a large group of cousins.
Equal shares can then create very unequal burdens. If only one sibling works in the business, that person bears the day-to-day responsibility. The others, however, may still have an equal say over investments and dividends. So while the shares may be equal, that does not necessarily make the arrangement fair.
The desire to be fair is therefore rarely the real issue. The harder question is what fairness means in practice. Children who do not work in the business might receive property, cash or other assets instead. Statutory inheritance rights also have to be taken into account.
Willi recalls a father who set up a business for each of his two sons and linked them through a holding company. Each son eventually took over one of the businesses.
The lesson is simple: fairness is not always the same as equality. Roles matter, as do risk and responsibility.
Each of these four assumptions can stand between a family and a successful handover. That is what makes them dangerous.
Good succession planning starts with an assessment of the situation. Where do the family and the business stand? Who is able and willing to take over?
Then comes the longer view. Where should the business be in ten years? Who should lead it? Should leadership remain within the family or be handed over to outside management? Or would a sale make more sense?
Once those questions have been answered, the family needs a clear timetable for the handover. Regular discussions can help determine whether the plan is on track or needs to be adjusted.
At the end of "The Cherry Orchard", the family has lost the estate and goes its separate ways. In the confusion, an elderly servant is forgotten and left behind in the locked house - another casualty of a decision deferred for too long.
"Succession is only successful if everyone is still speaking to each other afterwards and the family has not been torn apart by it," says Willi.
Wealth planning is particularly important in complex financial situations, for example where family assets are held across several generations in different countries and are subject to varying conditions, or where individual family members have different needs, values and goals.
Find out more about our wealth planning services for high-net-worth families here: